Short answer
Usually not. Homeowners policies generally exclude motor vehicles, so cleanup inside a car, truck, or van is normally evaluated under an auto policy instead. Comprehensive or collision coverage may respond depending on what happened, and a carrier may decide the vehicle is a total loss rather than pay for remediation. Call the auto carrier first and get its position in writing.
Why your homeowners policy is probably the wrong place to start
Most homeowners forms carve out motorized vehicles almost entirely. The car parked in your garage is treated as its own risk, insured under a separate auto policy with its own coverages and deductibles.
That surprises many families, especially when an incident happened in the driveway or garage. The location feels like part of the home, but the damaged property is the vehicle. A homeowners adjuster may look at a stained garage floor, while the seats, carpet, and headliner go to the auto carrier.
There are narrow exceptions. Some homeowners policies extend limited coverage to certain unregistered vehicles, golf carts, or equipment used on the property. An RV, camper, or boat may have its own policy entirely. Read your declarations pages side by side, and ask each carrier directly which one owns the question.
Which auto coverages might apply?
Auto policies usually split physical damage into two parts. Collision addresses damage from hitting another vehicle or object. Comprehensive, sometimes called other-than-collision, addresses many non-crash events, such as theft, vandalism, fire, and certain animal damage.
A bodily-fluid incident after a crash may be reviewed alongside the collision claim. An incident that happened while the car was parked, such as an unattended death, a break-in, or vandalism, is more often looked at under comprehensive. Whether either applies depends on your form, your exclusions, and whether you bought that coverage at all. Liability-only policies generally do not pay for your own vehicle.
- Collision: may be considered when contamination follows a crash that is already being claimed
- Comprehensive: may be considered for non-crash events like vandalism, theft, or a death in a parked vehicle
- Rental reimbursement: may help cover transportation while the vehicle is out of service, if you carry it
- Liability only: typically covers damage you cause to others, not cleanup inside your own car
Why an insurer may total the vehicle instead
Every physical damage claim is weighed against the vehicle's actual cash value. If the cost of remediation, parts, and labor approaches that value, the carrier may decide it is cheaper to settle the car as a total loss. The threshold differs by carrier and by state.
Cabin remediation can be expensive relative to an older vehicle's value because contaminated foam, carpet, padding, and sometimes headliner or HVAC components need to come out. A ten-year-old sedan may not justify that work on paper, even if it runs perfectly.
A total-loss decision is not always bad news. It can spare you from living with a vehicle that carries painful associations. If you want to keep the car anyway, ask whether you can retain it for a salvage deduction, and what title brand your state would apply. Title rules vary by state and county; verify with the local authority, usually the motor vehicle agency.
How a claim unfolds: an illustrative case
To make this concrete, here is an illustrative case; Marcus is not a real client. Marcus, a rideshare driver, picks up a passenger late at night who becomes ill and bleeds from a head injury after a fall at the curb. The passenger is taken by ambulance. Blood has soaked into the rear bench, pooled in the seat track, and stained the carpet behind the driver's seat.
Marcus stops driving immediately and does not try to shampoo the seat, since that could push fluid deeper into foam. He photographs the rear cabin, notes the trip details in the app, and calls two parties: his personal auto carrier and the rideshare platform. The platform may have its own cleaning-fee process, and his personal policy may treat commercial use differently than personal driving.
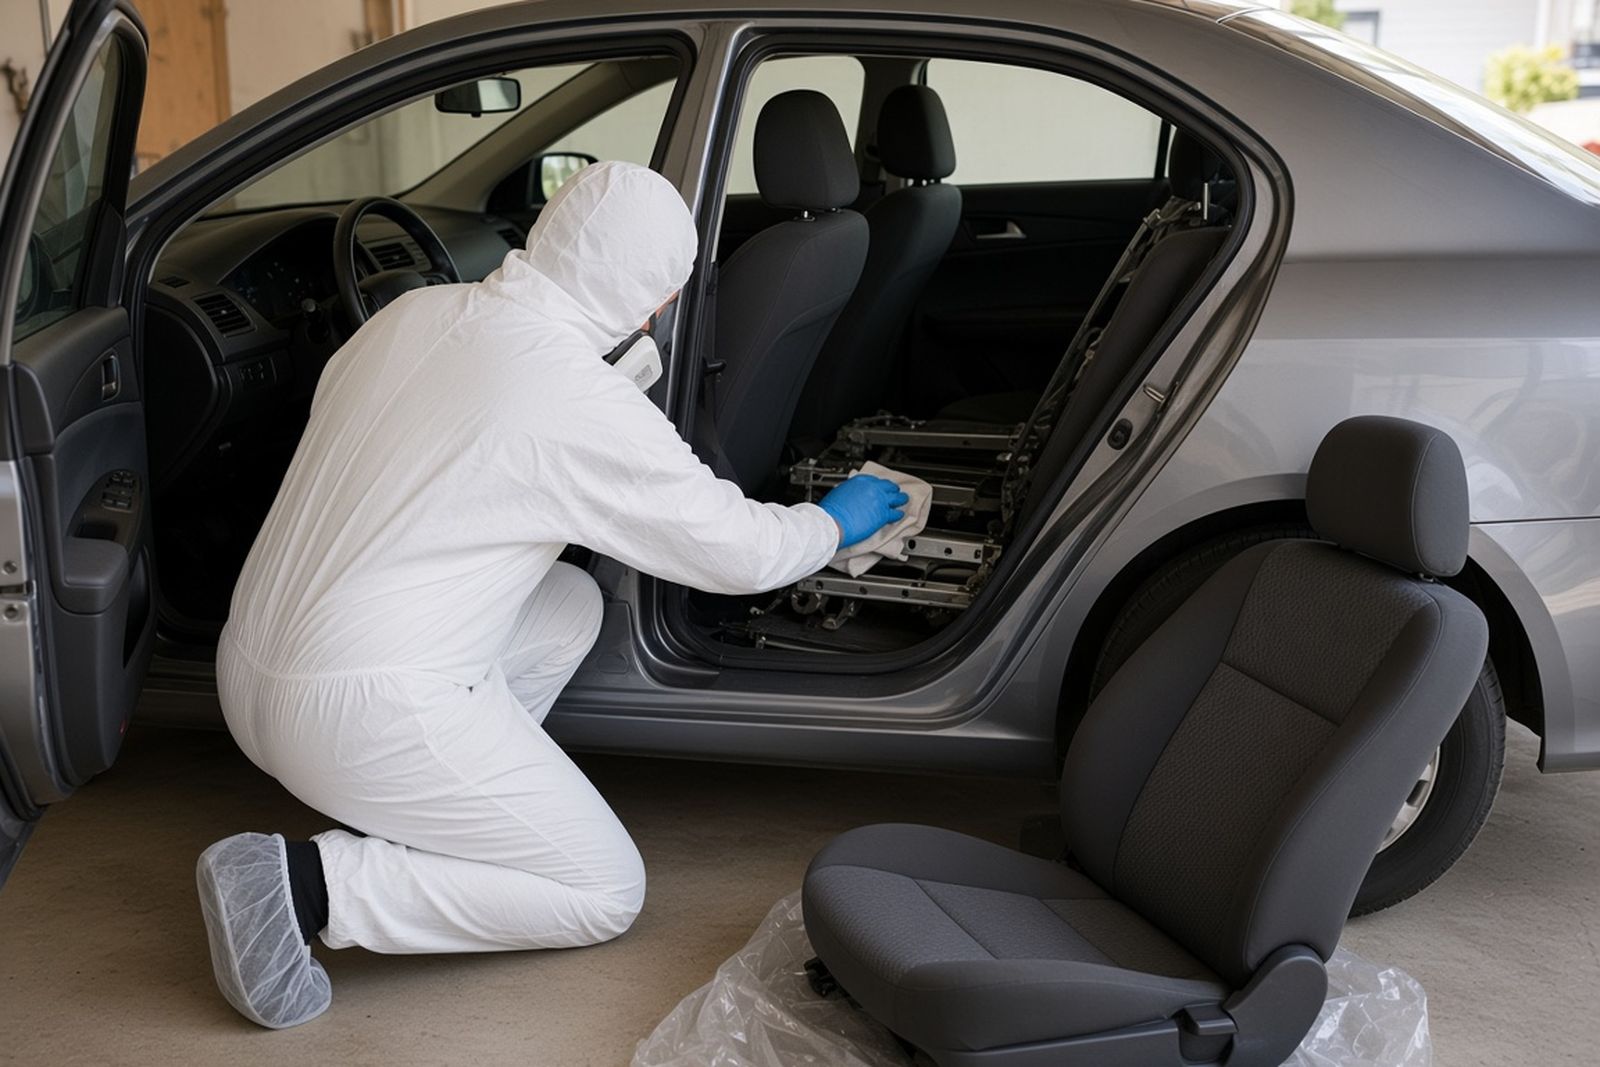
A vehicular biohazard technician inspects and writes a scope that separates removal of the rear seat foam, carpet and pad replacement, disinfection of the metal floor pan and seat rails, and cleaning of the rear HVAC vent. Marcus sends that scope to each party and asks, in writing, which items each one will evaluate. He does not assume anything is covered until he has those answers.
Does it matter who was in the car or how they were hurt?
It can. When a death or serious injury occurred, police, a medical examiner, or a coroner may need to release the vehicle before any cleanup begins. Do not start remediation, or let anyone else start, until you have confirmation that the vehicle is released.
If the incident involved a suicide, the carrier will usually treat it like any other covered event under the applicable coverage part. You do not have to explain more than the adjuster needs to process the claim. If you or someone close to you is struggling, you can call or text 988 to reach the 988 Suicide and Crisis Lifeline at any hour.
Commercial and fleet vehicles add another layer. A delivery van, ambulance, or company truck is usually insured under a business auto policy, and the employer's workers compensation carrier may be involved if an employee was hurt. Fleet managers should route the claim through whoever handles the company's insurance program rather than filing independently.
Documentation that helps an auto adjuster
Adjusters need to see how far contamination traveled, not just the stain on the surface. Photograph before anything is touched, unless there is an urgent safety reason to move the vehicle.
Keep the car closed and parked out of direct sun if you can. Heat speeds odor and can make the cabin harder to assess.
Avoid sitting in the affected seat or running the blower on high while you wait. Air moving through the cabin can carry odor and fine residue into vents and fabrics that were not part of the original incident, which widens the scope and the bill.
If the vehicle has to be towed, tell the tow operator what happened before they arrive. They may want to wear gloves, cover the seats they touch, or send a different truck, and a note on the tow ticket becomes one more piece of your claim record.
- Exterior photos showing the plate, VIN sticker, and overall condition
- Interior photos from each door opening, then close-ups of every affected seat, belt, and panel
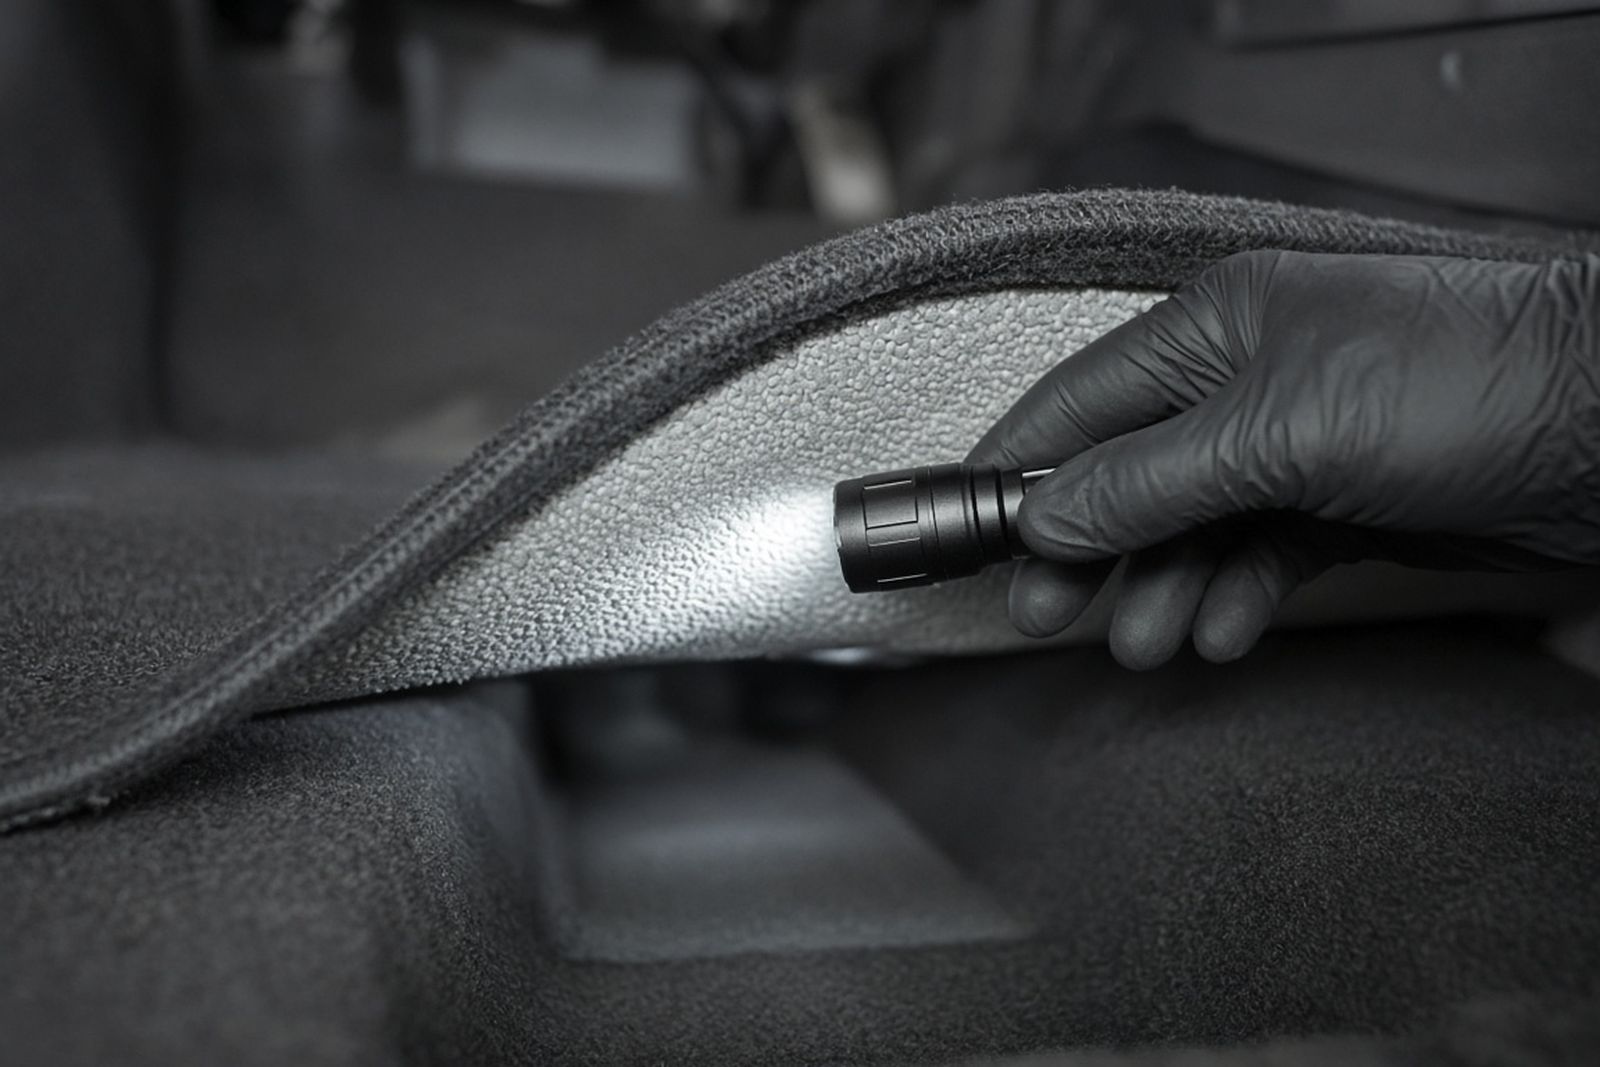
- Photos under seats and along seat tracks, where fluid often collects unseen
- Police report, incident number, or medical examiner case number if one exists
- The remediation company's written scope listing each component to clean or replace
- Any receipts for towing, storage, or a rental vehicle
Detailing instead of a claim
You can, but think about what detailing actually does. A detail makes the interior look and smell clean. It does not reach foam cores, carpet backing, or the floor pan, and it does not include a regulated waste route for saturated materials.
Some pathogens stay infectious on surfaces long after a spill dries, which is one reason a proper scope removes porous materials that cannot be verified clean, rather than scenting over them.
Skipping the claim may still make sense for a small, contained incident on a hard surface. Ask a remediation provider for an honest assessment before you decide, and ask whether the job is small enough that filing would cost you more in deductible and premium than it returns.
Questions for the auto carrier before work begins
Call, take notes, and follow up by email with a summary of what you were told. Crashes are common enough that carriers handle vehicle claims every day. NHTSA reports that police reported an estimated 6.18 million traffic crashes in the United States in 2024. Biohazard cleanup inside a cabin is less common, so the adjuster may need your help understanding the scope.
- Which coverage part are you evaluating: collision, comprehensive, or something else?
- Will you inspect the vehicle before any seats, carpet, or trim are removed?
- Is there a threshold at which you would consider the vehicle a total loss?
- Do you pay the remediation provider directly or reimburse me?
- Does my rental reimbursement coverage apply while the vehicle is out of service?
- If the vehicle is totaled, can I keep it, and what would the salvage deduction be?
If the carrier says no
Request the denial in writing, including the specific policy language. Sometimes a denial reflects a missing document or an incomplete scope rather than a true exclusion, and a clearer estimate can change the outcome.
If you still disagree, ask about reinspection, appraisal, or your state insurance department's complaint process. If you decide to pay directly, get at least two written scopes, compare what each one removes versus only cleans, and ask how the provider will confirm the cabin is ready for the next person to sit in it.